Blog
November 4, 2026
von
Andrej Evtimov
Four drivers behind the trend, and seven things the file can do before trial.
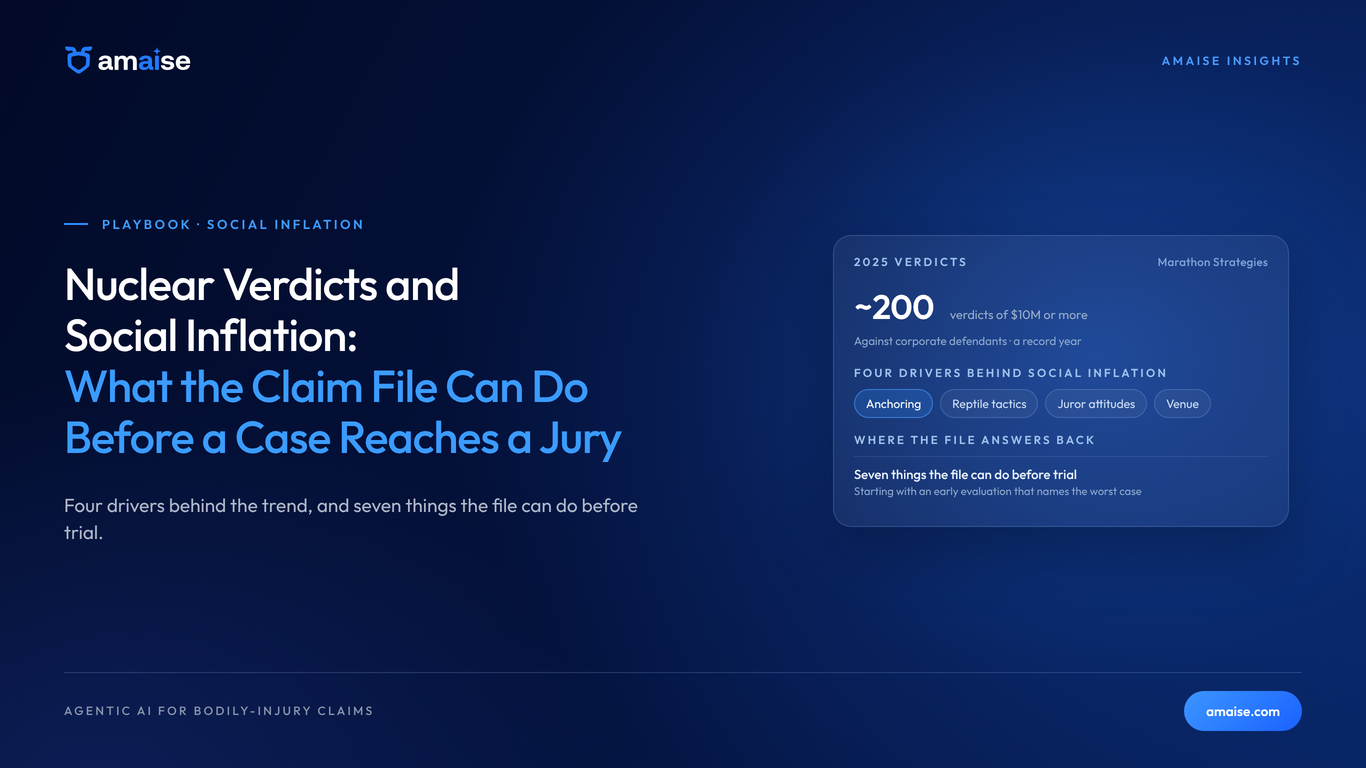
Nuclear verdicts reached a record number in 2025, and social inflation keeps pushing liability costs up. This post sets out the pre-trial claim file work that shapes exposure before a jury ever sees the case.
What nuclear verdicts and social inflation mean in 2026
Nuclear verdicts are jury awards of $10 million or more, and their number hit a record in 2025. A claim file cannot stop that trend. It can show early what a case could be worth at trial, and what the carrier did about it.
Marathon Strategies counted nearly 200 verdicts of at least $10 million in 2025 against corporate defendants, a 40.7% increase over 2024. Together they totaled $25.6 billion across 28 states. More than 40 exceeded $100 million, and four exceeded $1 billion.
The record is in the count, not the dollars. Marathon's prior report counted 135 nuclear verdicts in 2024, and those awards totaled $31.3 billion. Insurance Journal, reporting the 2025 data, put product liability at 29 verdicts totaling $12 billion. Trucking and automotive cases produced 12 verdicts totaling $3.4 billion.
Social inflation is the wider cost trend those verdicts feed. It describes liability claim costs rising faster than economic factors alone would explain. The Swiss Re Institute put US social inflation at about 7% in 2023, a 20-year high. It also estimated that social inflation raised US liability claims by 57% over the past decade.
The Insurance Information Institute and the Casualty Actuarial Society used a different method. Their 2025 analysis attributed $231.6 billion to $281.2 billion in added liability losses over ten years to what it calls legal system abuse. Severity, not frequency, drove the increase.
Four drivers behind social inflation
Social inflation has several causes, and most of them meet in the courtroom. A claim file cannot change them, but it can anticipate how each will be used.
Anchoring
Plaintiff counsel names a number, and that number shapes the award. In a 2000 mock-jury study, Marti and Wissler found larger plaintiff requests raised awards until the request became extreme. A 2025 Swiss Re behavioral study of 1,150 US adults found a similar pattern. Defense counter-anchors moderated expectations but did not remove the risk of a nuclear verdict.
Reptile tactics
The Reptile approach comes from a 2009 book by jury consultant David Ball and plaintiff lawyer Don Keenan. Counsel gets defense witnesses to agree to broad safety rules, then shows the defendant broke them. The rules are often generic, such as rules of the road, and may not match the facts of the loss. The American Bar Association describes how defense counsel expose and limit the tactic at deposition and trial.
Juror attitudes
In the Swiss Re survey, 85% of respondents said large corporations put profit ahead of safety. Some 79% favored punitive damages against large corporations. Only 56% said there are too many lawsuits, down from 90% in 2016. In its simulations, 30% of respondents returned verdicts above $10 million against large corporations, and 25% against smaller firms. These are survey respondents, not seated jurors, so read the figures as a direction, not a forecast.
Venue
Where a case is tried matters. Insurance Journal's report on the Marathon data put Florida at $2.5 billion in nuclear verdicts in 2025. The American Tort Reform Foundation's 2025-2026 Judicial Hellholes report ranks Los Angeles first and New York City second. That list is advocacy, and scholars such as Elizabeth Thornburg have criticized its method. Treat it as a prompt to check local verdict data, not as data.
State law moves the picture too. Florida's 2023 amendments, part of HB 837, added section 768.81(6). It bars recovery by a negligence plaintiff found more than 50% at fault, with medical negligence excluded. Georgia's SB 68, signed April 21, 2025, limits when counsel may argue a dollar figure for noneconomic damages. It also lets a party demand separate liability and damages phases. Which cases each change reaches depends on dates and facts, so confirm current law with counsel.
What the claim file can do before a case reaches a jury
No file controls a jury. The file shapes what the defense can show, how early the carrier saw the exposure and whether it acted. That record shapes settlement value long before a trial date. It can also matter in any later bad faith claim if a verdict lands above limits.
Briana Ford, AVP and Head of Excess Claims at Xceedance, asks one question on every file. She explains it on Claims Convos, a video series produced by amaise. If this case produced a nuclear verdict tomorrow, what was missed? The seven steps below are one way to answer that question early.
1. Run an early evaluation that names the worst case
Most evaluations estimate the likely settlement. Add a second figure: the plausible verdict range in this venue if liability goes badly. Record the facts that drive it, such as injury severity, a sympathetic plaintiff, a corporate defendant or a safety-rule story.
Kim Moody, VP and Head of Claims at Golden Bear Insurance Company, names the main obstacle on Claims Convos. "The biggest enemy of recognizing exposure is our own biases." She uses 30, 60 and 90-day litigation checkpoints. A fixed review date forces the worst-case figure to be revisited instead of left at its first-notice level.
2. Assess the venue from the file, not from a list
Put venue facts into the evaluation from the first review. Where can suit be filed? Where does the claimant live, where did the loss occur, and where is the insured based? Could a corporate co-defendant be joined to reach a preferred court?
Ask defense counsel for recent verdicts in that court on similar injuries. Ask which recent state law changes apply to this loss, such as Georgia's SB 68 or Florida's 2023 amendments. A venue note with dated facts is more useful than a ranking.
3. Document liability the way a jury will hear it
Reptile cases are often built at deposition, using the insured's own employees. Read the file for the safety rules opposing counsel will try to establish. Typical sources are company policies, training records, hours-of-service logs and maintenance records. Find where the insured complied and where it did not, before a witness is asked under oath.
Preserve the evidence early. In federal court, Rule 37(e) allows measures when electronically stored information that should have been preserved is lost. It applies when reasonable steps were not taken and the data cannot be restored or replaced. The harshest sanctions require intent to deprive. State spoliation rules differ. In auto files, the data at risk often includes dashcam footage, telematics and dispatch messages. Ask counsel when the duty to preserve starts and what the preservation notice should say.
The log notes are evidence too. Mike LaFond, Assistant Vice President of Claims at Pekin Insurance, puts it simply on Claims Convos. "Take notes like it's gonna be read aloud in court." He has been deposed over a note that said one thing while actions in the field said another. Claim notes can be discoverable. In federal court, work-product protection under Rule 26(b)(3) can yield to substantial need, and state privilege rules vary.
4. Build the damages record from the medical file
A plaintiff's anchor is a number with a story behind it. A defense counter-anchor needs its own story, grounded in the records. Start with a full medical chronology built from the claim file. Treatment gaps, prior complaints and changes in diagnosis should each carry a date and a source page.
Separate billed from paid amounts, and past care from projected future care. What a jury may hear about medical bills depends on state law. Florida's section 768.0427, also from 2023, limits evidence of satisfied past medical bills to the amount actually paid. It also requires disclosures for treatment under a letter of protection. In practice, a counter-anchor carries more weight when defense counsel can tie each figure to a page in the record.
5. Answer demands on time and in writing
How a carrier handled a policy limits demand often becomes the focus of a later bad faith claim. State rules differ, and the two below are examples, not a national rule. Georgia's O.C.G.A. 9-11-67.1 requires pre-suit time-limited offers in motor vehicle injury claims to stay open at least 30 days. The section has been amended more than once, so check the current text.
Florida's section 624.155(4), added by the 2023 amendments, sets a 90-day safe harbor. No liability bad faith action lies if the insurer tenders the lesser of limits or the demand in that window. The window runs from actual notice of a claim with sufficient supporting evidence. Under section 624.155(5)(a), mere negligence alone is insufficient to constitute bad faith.
This is general information, not legal advice. Confirm the current rules in each jurisdiction with coverage or defense counsel. The 30-day playbook for time-limited demands covers the day-by-day response. For nuclear verdict risk the point is narrower. Each decision, and the reason for it, belongs in the file on the day it is made.
6. Keep the reserve in line with the evaluation
A reserve that sits at its first-notice level while the evaluation climbs tells a story no one wants told later. Actuarial standards do not govern the adjuster's case reserve, but they rely on claim information. ASOP No. 43 directs actuaries to consider significant changes in conditions, particularly with regard to claims. It lets them rely on information from others unless it appears unreasonable.
When the worst-case figure moves, review the case reserve. Record why it changed, or why it did not. The post on how early file review changes reserve development covers the mechanics.
7. Make the early resolution decision on the record
Represented claimants take longer to close. The Insurance Research Council found the litigation rate among auto injury claimants rose from 10% to 18% between mid-2017 and mid-2022. Represented bodily injury claimants waited a median of nearly 440 days for closure, more than double the unrepresented.
Early resolution is not always the right call. Some claims should be defended. The file should show which path was chosen, by whom, on what evidence and when it will be reviewed again. A CLM Focus 2025 panel discussed stopping nuclear verdicts before trial, as the session recap reports.
A pre-trial checklist for nuclear verdict exposure
- First 30 days. File question: What is the worst-case verdict range in this venue? What to record: Venue facts, injury severity, likely defendants.
- First 30 days. File question: Has the evidence been preserved? What to record: Preservation steps agreed with counsel, with dates.
- Liability review. File question: Which safety rules will the plaintiff argue? What to record: Policies, logs, training, compliance gaps.
- Damages review. File question: What will the defense counter-anchor rest on? What to record: Chronology, billed vs paid, prior history.
- Any demand. File question: Was the response on time and on its terms? What to record: Deadline, coverage position, written reply.
- Each checkpoint. File question: Does the reserve match the evaluation? What to record: Reserve change and the reason for it.
- Before mediation. File question: Settle or defend, and why? What to record: Decision, authority, next review date.
Reading a long file for these points takes time an adjuster rarely has. An agentic AI platform for claim files uses specialized agents to process the file, with each finding linked to its source page. The adjuster still makes the evaluation.
Where the evidence runs out
Verdict counts measure jury awards, not final payments after post-trial motions, appeal or settlement. Marathon's counts come from its own tracking of publicly reported verdicts. Swiss Re and the III and CAS estimate social inflation with different methods, so their figures are not interchangeable. Survey respondents are not jurors. And no claim file can predict what a particular jury will do.
The state rules above are examples and change often. Treat them as prompts for a conversation with counsel, not as legal advice.
The file's job is narrower and more useful. It shows that the carrier saw the exposure early, acted on it, and can prove both. That is the part of nuclear verdicts and social inflation a claims team can actually control before trial.
Common questions
What counts as a nuclear verdict?
Marathon Strategies defines a nuclear verdict as a jury award of $10 million or more. Its counts cover verdicts against corporate defendants. Other trackers use different thresholds and samples, so check the definition before comparing figures.
Is social inflation the same thing as nuclear verdicts?
No. Social inflation is the broader rise in liability claim costs beyond economic inflation. Nuclear verdicts are one visible driver. Attorney involvement, longer claim duration and larger settlements below the nuclear threshold also contribute.
Can claim file work prevent a nuclear verdict?
It cannot guarantee an outcome. Early evaluation, venue assessment, documented liability and damages, timely demand responses and accurate reserves can support better settlement decisions. They also leave a documented record if a case with nuclear verdict potential goes to trial.
Key takeaways
- Nuclear verdicts (jury awards of $10 million or more) against corporate defendants reached a record of nearly 200 in 2025, up 40.7% on 2024, per Marathon Strategies.
- Swiss Re put US social inflation at about 7% in 2023, a 20-year high, and anchoring, Reptile tactics, juror attitudes and venue feed it.
- The claim file cannot control a jury, but it shapes what the defense can show and how early the carrier saw the exposure.
- Seven file steps are covered here: worst-case evaluation, venue facts, liability evidence, a sourced damages record, timely demand responses, reserve alignment and a documented resolution decision.
- State law varies widely, including Florida's 2023 amendments and Georgia's 2025 SB 68, so confirm current rules with counsel.